

Budget App — PocketGuard
by PocketGuard, Inc.
4.5
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.5
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
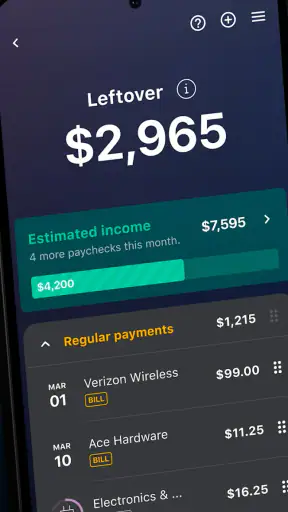
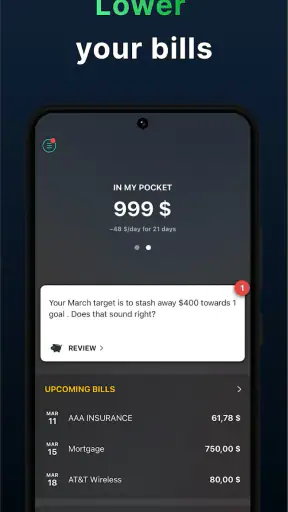
I approached PocketGuard as someone trying to make sense of everyday spending rather than as a finance expert. That distinction matters. This is a budgeting app from PocketGuard, Inc. built around a simple question: after regular bills and planned spending, how much money can I safely use? For a first-time user, that promise is more useful than a screen crowded with charts, provided you are willing to give the app enough information to make the picture meaningful.
The app is free to download and is suitable for Everyone, which makes it approachable for students, households, and anyone who wants a clearer view of personal finances. It also includes optional in-app purchases ranging from under a dollar to well over a hundred dollars per item, so I would look carefully at the purchase screen before committing to anything beyond the basic experience. The Android release has been available since mid-March 2016, and the current version is 5.19.3 for devices running Android 8.0 or later.
Getting from installation to a useful budget
I’d use the first setup session to build a dependable baseline, not to make the budget look polished: enter the income you count on and the regular costs that shape your month. Once that picture is in place, the next section looks at what to check when you start using it for everyday spending.
What to expect when you open it
PocketGuard is not best understood as a digital envelope stuffed with complicated rules. I found its appeal in the way it tries to turn several financial details into one practical spending view. You can use it to follow income, keep an eye on expenses, and work toward saving money without needing to build a spreadsheet from scratch.
That convenience also creates an important expectation: the app is only as helpful as the information behind its calculations. If income is entered incorrectly, a recurring bill is forgotten, or a transaction is categorized badly, the amount that looks available can become misleading. I would treat the main figure as a planning aid, not permission to spend every cent shown.
The audience is broad, but the strongest fit is someone who wants regular awareness rather than a highly technical accounting system. If you mainly need to know why your bank balance changed and where your money is going, the app has a clear purpose. If you manage a small business, reconcile accounts for tax work, or need detailed investment analysis, a specialized finance tool will probably suit you better.
PocketGuard has built a noticeable user base, with an average rating of 4.5 from around 2.9 thousand ratings and more than a thousand written reviews. Those figures suggest that many people find the approach approachable, although a rating cannot tell you whether the app matches your own banking habits or tolerance for manual corrections.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Setting up the first useful picture
I would begin slowly instead of trying to configure every possible detail in one sitting. Start with the income you actually rely on, then add the bills and regular expenses that shape the month. The goal of the first session is not perfect financial organization. It is to create a believable baseline that can answer one immediate question: what can I spend after the obligations I already know about?
When entering recurring costs, use the amount you normally pay rather than an unusually low month. A rent payment, subscription, loan installment, or utility bill that is missing from the picture can make the app’s available-money view look more comfortable than reality. For variable costs, I would use a cautious estimate and review it after a couple of weeks rather than pretending the number is exact.
The same principle applies to income. Someone paid monthly can think in monthly terms, while a person paid weekly or irregularly should be especially careful about how payment timing affects the plan. A budget can look healthy across a full month and still feel tight during the days before the next deposit. I would use PocketGuard alongside the calendar, not as a replacement for it.
One practical habit is to set up the app before a normal spending day, not during a rushed checkout. That gives you time to recognize unfamiliar categories and correct obvious mistakes. It also makes the first result easier to trust because you are not making decisions while distracted.
The first meaningful success
For me, the first successful action would be checking one ordinary purchase and learning what it does to the rest of the month. Buy groceries, record or review the transaction, and then compare the updated spending view with your own expectation. If the result feels wrong, do not immediately blame the calculation. Check whether the purchase landed in the right category and whether a regular expense was overlooked during setup.
This small test is more valuable than filling the app with a long list of goals on day one. It teaches you how PocketGuard reflects real behavior. Once the basic picture makes sense, you can use the spending information to decide where a modest adjustment is realistic. For example, reducing a flexible category by a manageable amount may be more useful than setting an ambitious savings target that collapses after one unexpected expense.
A helpful workflow is to review the app after a purchase that you would normally forget, such as a takeaway meal, a digital subscription, or a small household item. These are the transactions that often disappear from memory while quietly adding pressure to a monthly plan. PocketGuard is most useful when it turns those small decisions into visible feedback without requiring you to perform a full financial review every evening.
I also recommend separating “available to spend” from “money I own.” The former is a short-term planning idea; the latter may include funds reserved for bills, emergencies, or goals. Keeping that distinction in mind prevents one of the most common budgeting mistakes: treating a positive balance as proof that every purchase is affordable.
Where new users can become confused
The first area that may cause friction is the difference between a transaction and a recurring obligation. A single purchase tells you what happened. A recurring expense tells the app what is likely to happen again. If you only focus on past transactions, the forward-looking part of the budget can be incomplete. I would review the recurring section whenever a bill changes, ends, or moves to a different payment date.
Categories can also create uncertainty. A purchase may fit more than one description, and an incorrect category can distort the way you interpret your habits. I would not obsess over perfect labels for every small transaction, but I would correct categories that affect decisions. A forgotten grocery purchase is not the same planning problem as a forgotten annual payment, even if both appear as expenses.
Another source of confusion is the temptation to read the app’s summary as a final verdict. Budgeting involves timing, irregular costs, and personal priorities. A screen can show a useful estimate, but it cannot know that you are planning a birthday gift next week unless you account for it. Before making a large purchase, I would mentally reserve money for upcoming events and bills that have not yet appeared.
People who share finances may need an extra layer of discipline. If two people spend from the same household funds but only one checks the budget, the picture can become outdated quickly. In that situation, the app can still support a shared routine, but it should not be treated as an automatic agreement between partners. Decide who reviews transactions, how corrections are handled, and when the household checks the plan together.
How it compares with familiar alternatives
The usual alternative is a bank app. A bank application is excellent for confirming balances and completed transactions, but it often leaves the user to interpret what those numbers mean for the rest of the month. PocketGuard’s budgeting focus is more useful when the question is not “what is my balance?” but “what can I reasonably use after the commitments I have listed?”
A spreadsheet offers more control. You can create any categories, formulas, and long-term views you want, which is valuable for people who enjoy detailed customization. The trade-off is maintenance. A spreadsheet depends on consistent manual updates and can become stale after a busy week. PocketGuard is the easier choice when you want a guided financial overview rather than a project to manage.
Traditional envelope budgeting can be more motivating for someone who prefers strict limits for groceries, entertainment, and other categories. PocketGuard feels less like physically dividing money into separate envelopes and more like observing the relationship between income, expenses, and remaining flexibility. I would choose the envelope method if category boundaries are the main thing that keeps you disciplined; I would choose this app if a broad, current spending picture is what you keep losing track of.
There is also a difference between a budgeting app and a full financial planner. PocketGuard is focused on everyday money management. It can help you notice spending pressure and make a savings decision, but it should not be your only tool for complex investing, business bookkeeping, or formal financial reporting. Knowing that boundary is part of using it well.
Making the routine stick
After the first successful check, I would create a short weekly routine. Pick a quiet moment to review recent spending, look for a changed bill, and compare the app’s picture with your actual plans for the coming days. This is enough to catch many problems before they become end-of-month surprises. A daily review may be unnecessary for some people, while a monthly-only review can be too late.
Use the app to support a decision, not to produce guilt. If spending is higher than expected, identify the cause before cutting everything indiscriminately. A one-time repair, a social event, and a growing subscription habit require different responses. The useful insight is not simply that you spent more; it is whether the pattern is temporary, predictable, or easy to change.
One less obvious trade-off is that convenience can reduce attention. When an app summarizes finances for you, it is easy to trust the summary without understanding its ingredients. I would occasionally inspect the underlying expenses and income rather than looking only at the headline amount. That habit keeps the tool accountable to your real life.
Another practical tip is to use a “planned surprise” mindset. You cannot predict every emergency, but you can acknowledge that irregular costs exist. Before deciding that all remaining money is free, leave room for expenses that arrive occasionally. This makes the budget less exciting on a good day, but much more resilient when the month becomes complicated.
Who should try it and who should skip it
I would recommend PocketGuard to a first-time budgeter who wants a clear starting point, especially someone who finds spreadsheets intimidating or who repeatedly reaches the end of the month wondering where the money went. It is also a reasonable fit for people who want to connect everyday spending with a savings intention without building a financial system from the ground up.
I would be more cautious if you dislike reviewing financial information, need absolute control over every formula, or have finances that do not fit a straightforward personal budget. People with irregular income can still use it, but they should be conservative and check timing carefully. Anyone using it for a household should agree on a review routine so that the app reflects everyone’s spending.
The free entry point makes experimentation easy, but optional purchases mean I would evaluate the basic workflow before paying for anything. Ask yourself whether the app helps you make a better decision after a normal week. If it does not, extra features are unlikely to fix a setup that does not match your habits.
My final take after using the budgeting approach
PocketGuard succeeds when it reduces the distance between raw transactions and a practical spending decision. I like that its purpose is easy to understand: organize income and expenses, keep regular commitments in view, and make saving feel connected to daily choices. Its strongest result is not a dramatic financial transformation; it is the quieter confidence that comes from knowing what deserves attention before you spend.
It is not effortless financial wisdom, and I would not use its available-money view blindly. The setup needs care, categories may need correction, and irregular expenses still require your judgment. Those are normal limitations of a budgeting tool, but they matter because a clean interface can make an estimate feel more certain than it really is.
With more than 100 thousand installs, an Everyone age rating, and a free starting point, it is easy to see why the app attracts newcomers. My advice is to install it with one modest goal: build a credible picture and test it against a real purchase. If that first comparison helps you understand your month better, keep the weekly routine. If you need detailed accounting or strict envelope controls instead, choose a tool designed around those priorities. For a first step toward more deliberate everyday spending, PocketGuard is useful when you treat it as a guide and stay involved in the decisions.
Pros
- Links bank accounts and cards for an up-to-date financial overview.
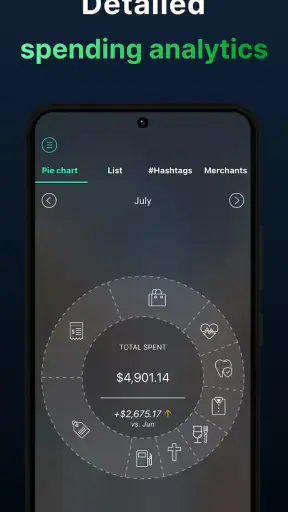
- Automatic categorization makes spending patterns easy to understand.
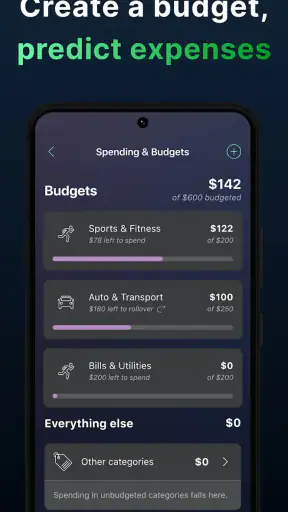
- Custom spending limits help prevent overspending between paychecks.
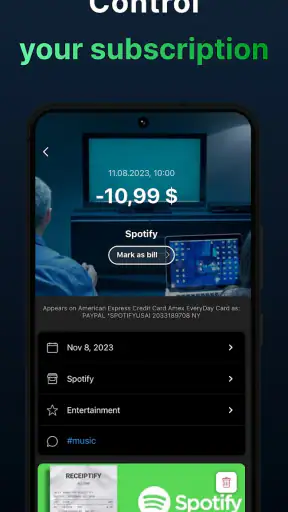
- Recurring bills and subscriptions are easier to monitor in one place.
- Clean interface makes core budgeting tools approachable for beginners.
Cons
- Many useful features require a paid PocketGuard Plus subscription.
- Bank connections may occasionally fail or need to be reauthenticated.
- Limited customization may frustrate users with complex budgeting systems.
- Automatic transaction categories can require manual corrections.
- Availability and supported financial institutions vary by country.
FAQs for Budget App — PocketGuard
What is PocketGuard, and how does it help with budgeting?
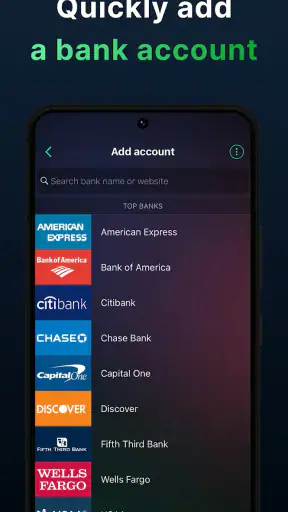
PocketGuard is a personal finance and budgeting app designed to help you understand where your money goes and how much you can safely spend. After connecting eligible financial accounts, it organizes transactions, tracks bills and recurring expenses, and estimates your available spending money. Its main appeal is providing a quick overview rather than requiring users to build every budget category manually.
Is PocketGuard safe to use with bank and credit account information?
PocketGuard uses account connections to import financial data, so users should review its privacy policy, security information, and supported connection providers before signing up. The app generally relies on established financial-data connection services rather than asking for unrestricted access to your bank account. Even so, no online service is completely risk-free, and you should enable device security, use a strong password, and monitor connected accounts regularly.
Does PocketGuard cost money, or is there a free version?
PocketGuard may offer both free and paid features, but the exact availability, pricing, and subscription terms can vary by platform, region, and current promotion. Basic budgeting tools may be accessible without payment, while advanced features such as expanded customization, additional financial planning options, or premium reports can require a subscription. Check the in-app purchase screen before starting a trial or confirming a recurring plan.
Can PocketGuard automatically track bills, subscriptions, and spending?
PocketGuard can help organize transactions and identify recurring payments when the relevant accounts are connected and supported. This makes it useful for spotting subscriptions, regular bills, and spending patterns that are easy to overlook. However, automatic categorization is not always perfect, especially for unusual merchants, transfers, refunds, or shared expenses. Review imported transactions and correct categories so the app’s budget estimates remain accurate.
What should I know before downloading PocketGuard?
PocketGuard is most useful for people who want a simplified view of their finances and an estimate of money available after regular obligations. It may be less suitable if you need highly detailed investment tracking, complex household budgeting, or complete manual control over every financial entry. You will also need to verify whether your bank or card provider is supported, since account connectivity can differ by country and institution.

Budget App — PocketGuard
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via android@pocketguard.com, visit https://pocketguard.com, or review their https://pocketguard.com/privacy/.










